There is a number that decides whether money feels tight or livable, even when income and bills stay exactly the same.
It is not the rent. Not the car payment. Not the student loans.
It is the amount set aside—on purpose—for everything that is not strictly necessary: takeout, hobbies, small splurges, the random Target wander. Call it fun money, non‑essentials, lifestyle spending. The label does not matter. The number does.
Get it wrong, and budgets explode or lives feel joyless. Get it roughly right, and the rest of the plan gets a lot easier to stick to.
This is a guide to choosing that number on purpose instead of by vibes.
—
Why “no fun” budgets usually fail
Plenty of budgeting advice quietly treats non‑essential spending as a moral problem: less is virtuous, zero is ideal. Real life does not cooperate.
Most people can white‑knuckle a “no fun” budget for a few weeks. Then life happens. A friend has a birthday. A bad day calls for comfort food. A hobby purchase pops up on sale. Without a clear allowance for this kind of thing, every purchase feels like a failure—and that feeling tends to send spending even further off the rails.
On the other side, there is the shrug approach: pay the bills, glance at the account balance, and hope there is enough for everything else. That often works only until a big card swipe or a run of small taps quietly eat next month’s rent.
A defined fun‑spending number is the middle path. It acknowledges that non‑essential spending is inevitable and legitimate, but not unlimited.
—
Step 1: Start from reality, not rules
Rules of thumb float around: 50/30/20, 80/20, “just cut lattes.” They can be rough reference points, but they do not know rent prices, childcare costs, or what actually matters in any one life.
A better starting point is a simple three‑line snapshot:
1. **Take‑home income for the month** (after tax and paycheck deductions). 2. **Essential expenses**: housing, utilities, food at home, basic transport, minimum debt payments, childcare, insurance premiums, and anything else that is genuinely non‑optional. 3. **Irregular but expected costs**, averaged to a monthly number: car repairs, medical co‑pays, annual subscriptions, holidays and gifts, school fees.
Subtract the second and third from the first. The number left over is the entire pot for:
– extra debt payments or investing – savings for near‑term goals – fun and lifestyle spending
There is no way around this arithmetic. If the leftover is painfully small, that is a signal that the issue is more “income vs. fixed costs” than “too many coffees.” But even in tight situations, shaping that leftover intentionally still helps.
—
Step 2: Decide what fun is *for* right now
Fun spending does more work than it gets credit for. It keeps burnout at bay, maintains social connections, and turns time into a life rather than just survival.
So the useful question is not “How can this be cut to the minimum?” but “What does fun spending need to do in this season?”
Some examples of “jobs” fun money might be hired to do:
– Stay connected to friends without blowing the budget – Keep one or two hobbies alive – Make a tough work schedule more bearable (takeout on late nights, for instance) – Give kids a few treats or outings
When the purpose is clear, trade‑offs get easier. If connection is the main job, weekly dinners out might be replaced with cheaper coffee catch‑ups or potlucks. The money is still social; the format shifts.
—
Step 3: Set a first‑draft number
With the leftover pot and the purpose in mind, it is time to choose a starting figure.
1. **Protect non‑negotiable progress**. Decide how much of the leftover goes to must‑dos beyond baseline essentials—this might include an emergency‑fund contribution, paying down high‑interest debt, or catching up on overdue bills. Those come off the top. 2. **Pick a percentage band, not a single rule**. Many households who are not in acute crisis land somewhere between **5% and 20%** of take‑home income on fun and lifestyle spending. On a $3,000 take‑home month, that is $150 to $600. The low end feels spartan; the high end starts to crowd out longer‑term goals. 3. **Choose a realistic number inside that band** based on current priorities. In a debt‑heavy season, the number might live closer to 5–10%. During a more stable period, 15–20% may be sustainable.
None of these figures are commandments. They are a frame. The real test is whether the chosen number fits both the math and the actual life being lived.
—
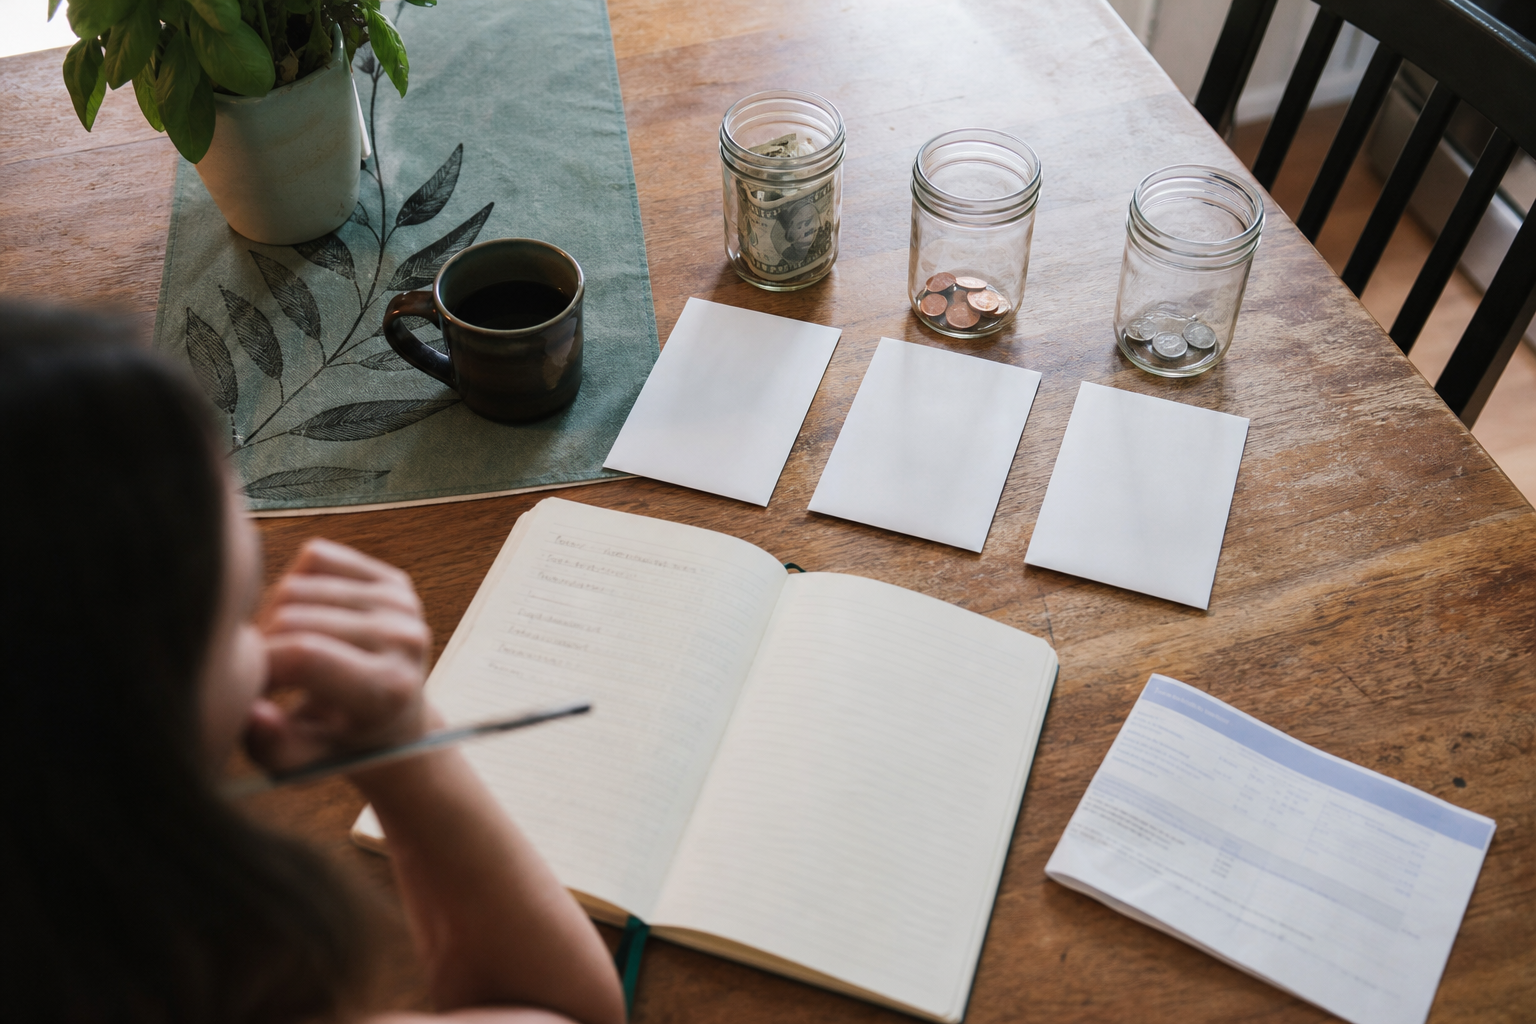
Step 4: Turn that number into something visible
A fun‑spending number only helps if it shows up where decisions are made—at the checkout counter, in the delivery app, at the weekend plan.
Two low‑maintenance ways to make it visible:
### 1. The “labeled bucket” method
– Set up a labeled account (or a prepaid card) named something like “Fun” or “Flex.” – Move the chosen amount in at the start of each month or each payday. – Only non‑essential purchases come from that bucket.
When the bucket empties, the fun spending is done until the next refill. There is no guessing whether the money is “extra.” It is either there or it is not.
### 2. The “weekly ration” method
Some people find a monthly number too abstract. In that case:
– Take the monthly fun total and divide by four or five, depending on the number of pay cycles. – That smaller weekly number becomes the allowance. – Reset the tally at the start of each week.
This works particularly well for those whose fun spending tends to spike on weekends.
These methods echo the idea of tracking burn rate in a broader budget. For readers interested in digging into that side of things, there is a deeper dive into how a burn‑rate budget works.
—
Step 5: Stress‑test against real life
The first version of a fun‑spending number is an experiment. Over the next month or two, it will run into real conditions.
Useful questions during that test:
– Is this level of fun money making it impossible to meet savings or debt goals? – Is there a particular category (restaurants, online shopping, hobbies) that blows the cap every time? – Does the number feel so tight that social life or mental health is taking a hit?
If the number is clearly too low, that is not a failure of willpower. It is a piece of information. The options then are:
– **Look for room in fixed costs.** Could a bill be renegotiated, a subscription canceled, a cheaper plan used for a while? – **Reorder priorities explicitly.** Some seasons do call for ultra‑lean fun budgets, but calling that out as a short‑term push (with an end date) is kinder than pretending it is a forever lifestyle. – **Shift the type, not the amount, of fun.** Free or low‑cost activities—library holds instead of impulse book buys, home dinners instead of every meal out—keep the spirit of fun without the same price tag.
If the number seems generous but debt or savings progress is stalling, trimming 5–10% from fun and reassigning it can make a visible difference.
—
Step 6: Build in personal rules that remove friction
The dollar cap is the core, but a couple of simple rules can keep the number working.
Examples readers often find useful:
– **A “pause” rule for bigger fun buys.** Any non‑essential purchase over a certain amount (say $75 or $100) waits 24 hours. If it still feels worth using a chunk of fun money, it passes. – **A “no double dipping” rule.** Once a fun item is bought on credit, it still counts against the fun‑spending cap that month, not some vague future. – **A “look ahead” rule.** If a known fun event is coming—a concert, a trip, a big night out—set aside part of the fun budget in advance so regular weeks do not feel starved.
These are not about self‑punishment; they are ways to avoid the specific habits that tend to blow the plan.
—
When the math just does not work
Sometimes the hard truth is that even ruthlessly trimmed fun spending cannot fix a gap between income and essentials.
Signs that may be the case:
– Fun spending is already near zero, but overdrafts and card balances keep growing. – Essentials like medicine or utilities are competing with each other. – Any small emergency immediately spills onto high‑interest debt.
In those situations, the fun‑spending number is still worth defining (even a tiny $10 or $20 can preserve some sense of control and joy), but the bigger project becomes changing the fundamentals: income, housing, transportation, debt structure.
That is a longer road. A clear, realistic fun‑spending cap will not solve it—but it can reduce the chaos while other pieces move.
—
A number that makes “yes” and “no” simpler
A well‑chosen fun‑spending number does not eliminate trade‑offs. It does something more practical: it moves those decisions out of the guilt‑fog and into the light.
Instead of wrestling with “Do I deserve this?” every time a small joy appears, the question becomes: “Does this fit inside the number chosen on purpose?”
If yes, enjoy it. If not, it becomes a conscious choice to say no—or to reshuffle and make room.
The income and the bills matter. But for day‑to‑day peace of mind, this quiet middle number—the one that funds the parts of life that do not show up on a credit report—often matters just as much.
About the Author