Car registration. The annual physical with the copay that somehow never matches last year’s. Holiday gifts. The dog’s teeth cleaning. None of these are surprises, exactly — they show up on a schedule, even if the schedule is fuzzy. And yet they tend to land like emergencies, because most budgets are built for the predictable weekly grind of groceries and gas, not for the lumpy, occasional costs that hit every few months.
That gap is where sinking funds live. The name sounds vaguely nautical and slightly ominous, but the concept is almost comically simple: instead of letting a big, irregular expense ambush a checking account once or twice a year, the cost gets broken into small monthly deposits ahead of time, so the money is already sitting there, waiting, when the bill shows up.
Why This Isn’t the Same as an Emergency Fund
It’s easy to lump sinking funds in with emergency savings, but they solve different problems. An emergency fund exists for the unknowable — a layoff, a medical scare, a car accident. A sinking fund exists for the knowable, the stuff that is 100 percent going to happen, just not this week. Property tax bills don’t qualify as emergencies. Neither does the fact that winter tires wear out, or that a kid’s school requests a few hundred dollars for a trip every spring.
Treating these predictable costs as emergencies tends to create a strange cycle: something foreseeable happens, it feels like a crisis because there’s no cash set aside, a credit card absorbs the hit, and then the next few months go toward paying that down — right up until the next “surprise” expense arrives and the cycle starts again. A sinking fund breaks that loop by moving the surprise out of the equation entirely.
Starting With a List, Not a Spreadsheet
The first step isn’t math — it’s memory. Grab a notebook, a notes app, whatever is handy, and spend fifteen minutes writing down every expense that isn’t monthly but is still pretty predictable. Common ones include:
– Car registration, inspection, and new tires – Annual or semiannual insurance premiums (home, auto, life) – Holiday spending and gifts – Back-to-school costs – Vet visits and pet grooming – Annual subscriptions paid as a lump sum – Home maintenance like gutter cleaning or HVAC servicing – Birthdays, anniversaries, and travel for family events
This list will look different for everyone, and that’s the point. A household without pets skips the vet line. A renter skips home maintenance. The goal isn’t to copy a generic list but to build one that actually reflects a specific life.
Turning the List Into Monthly Numbers
Once the list exists, each item needs two numbers: roughly how much it costs, and roughly how often it hits. Car registration might be $180 once a year. Holiday spending might land around $600 total across November and December. Vet visits might average $300 a year once routine checkups and one unplanned visit get averaged in.
From there, the math is just division. Annual cost divided by twelve gives the monthly amount to set aside. $180 a year for registration becomes $15 a month. $600 for holidays becomes $50 a month. $300 for the vet becomes $25 a month. Add those up across every item on the list, and the total is the monthly sinking fund contribution — the number that quietly absorbs all the “surprises” before they happen.
For a lot of households, this total lands somewhere between $100 and $400 a month, depending on how many irregular costs are in play and how expensive they are. That can feel like a lot at first glance, especially for a budget that’s already tight. It helps to remember that this money was always being spent — it just used to show up in unpredictable, stressful chunks instead of steady, boring ones.
Where the Money Actually Lives
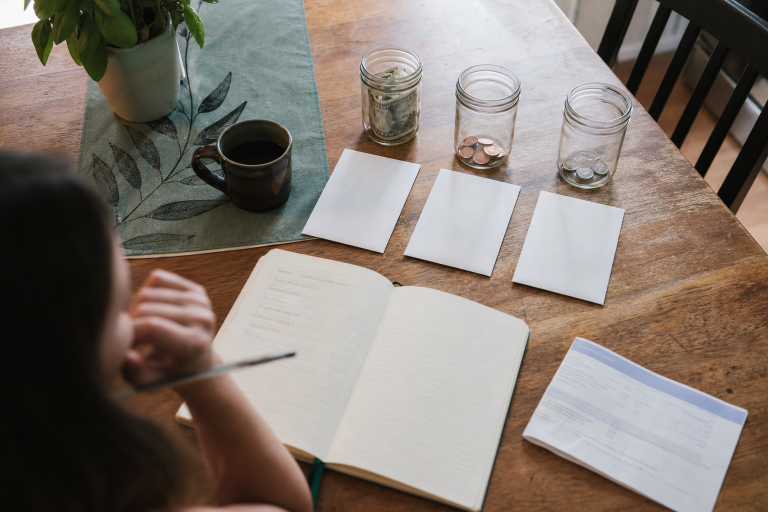
A sinking fund works best when it’s visible but not too easy to touch. Many banks and credit unions allow multiple named savings sub-accounts or “buckets” within one account, which makes this almost effortless: one bucket labeled “car stuff,” another labeled “holidays,” another for “pet care.” Seeing the balance tied to its purpose makes it far less tempting to raid for something unrelated, because pulling from “holiday gifts” to cover a night out comes with a very specific, very visible trade-off.
For those without access to sub-accounts, a single separate savings account with a simple spreadsheet or notes-app tracker does the job almost as well. The key is separation from everyday checking — money that’s easy to see but requires a deliberate transfer to spend.
Adjusting Without Starting Over
Sinking funds are not set-in-stone contracts. Costs shift. The dog needed two extra vet visits this year. The holiday budget crept up. None of that means the system failed — it means the numbers need a light touch-up, not a teardown. A quick review every few months, maybe during a regular monthly money check-in, keeps the estimates reasonably close to reality without turning into a second job.
It’s also fine to prioritize. Starting all ten categories at once can feel overwhelming, especially on a tight budget. Picking the two or three most stressful expenses — the ones that cause the most financial whiplash when they hit — and funding those first still delivers most of the benefit. The rest can be added gradually as the budget allows.
The Real Payoff
The quiet magic of a sinking fund isn’t really about the money. It’s about what stops happening: the dread that creeps in every October knowing the holidays are coming and there’s no plan, the mild panic when a mechanic says the words “you’ll need new brakes soon,” the scramble to move money between accounts right before a bill is due. None of that disappears instantly, but it fades fast once a few months of steady deposits build a cushion.
Eventually, these expenses stop feeling like emergencies and start feeling like what they actually are — routine. Annoying, sure. But routine. And routine is a lot easier on both the budget and the nervous system than constant, low-grade financial surprise.
About the Author